Construction under way of second Zhaoyuan unit
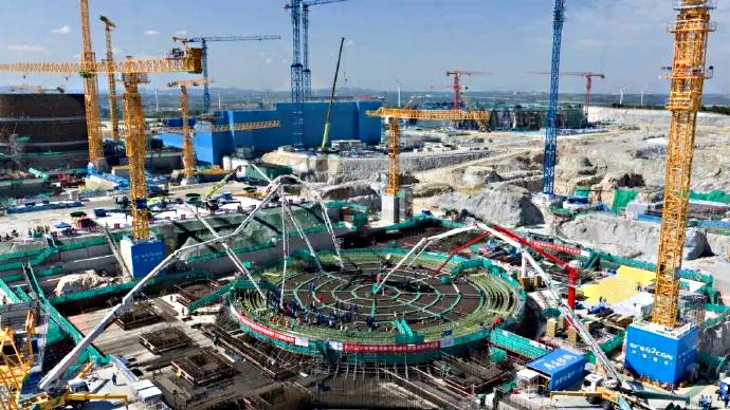
China has poured first concrete for the second reactor at its Zhaoyuan nuclear power plant in Shandong province. The Hualong One unit is the second of six planned for the site, with a total capacity of 7.2 GW expected to generate 50 TWh annually. Construction began in November 2025 for unit 1; unit 2's basemat pour started in September 2026, representing an investment of CNY120 billion. Each reactor is expected to reach operation 50 to 60 months after construction starts.
Where this fits
China is building firm, dispatchable, low-emission power at scale. Zhaoyuan alone will displace 46 million tonnes of CO2 annually while meeting the baseload demand of five million people with a single, compact site. Australia, by contrast, has chosen a renewables-only path: wind and solar are cheap per megawatt-hour, but the whole-system cost, firming gas, transmission overbuild, battery storage, and mineral extraction in China, is being front-loaded now. The firm-power alternative remains banned by law.
What it means
While China deploys firm nuclear capacity to anchor grid stability and industrial electricity supply, Australia remains dependent on weather-dependent generation backed by gas, all on a supply chain, panels, batteries, inverters, processed minerals, owned or controlled by Beijing. This is not a story about emissions. It is a story about energy sovereignty. China is choosing energy independence through firm, domestically-controlled generation. Australia is choosing energy dependence on the weather and on China's supply chain. The consequence compounds: as Australia's industrial base contracts for lack of cheap, firm power, China's grows.
By the numbers
enough for 15–24 TWh a year of firm, always-on power, generating for ~60 years. Source: CSIRO GenCost 2024-25 (A$8.5–13.2bn/GW), IAEA capacity factor.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
Go deeper on the numbers
The bigger picture
Energy security is national security. This connects to the wider case at Unprepared: Australia's dependence on a strategic rival, and how ready it is for the world that is coming.
Reported by World Nuclear News. Read the original report ↗
Related coverage
Centrus and Antares Sign Multi-Year HALEU Supply Contract
Rethink on nuclear leads to fresh uranium opportunities - Australian Resources & Investment
Foundations laid for major expansion of the Royal Navy nuclear submarine fleet - Navy Lookout
‘We’re going to miss the boat’: Labor pressed to reverse nuclear ban as AI booms - The Australian
The numbers, as they move
A short, sourced brief when the figures shift: a transmission blow-out, a supply-chain move, a milestone.