No roof left behind: how advanced solar technology can bring difficult commercial buildings into Australia’s energy transition
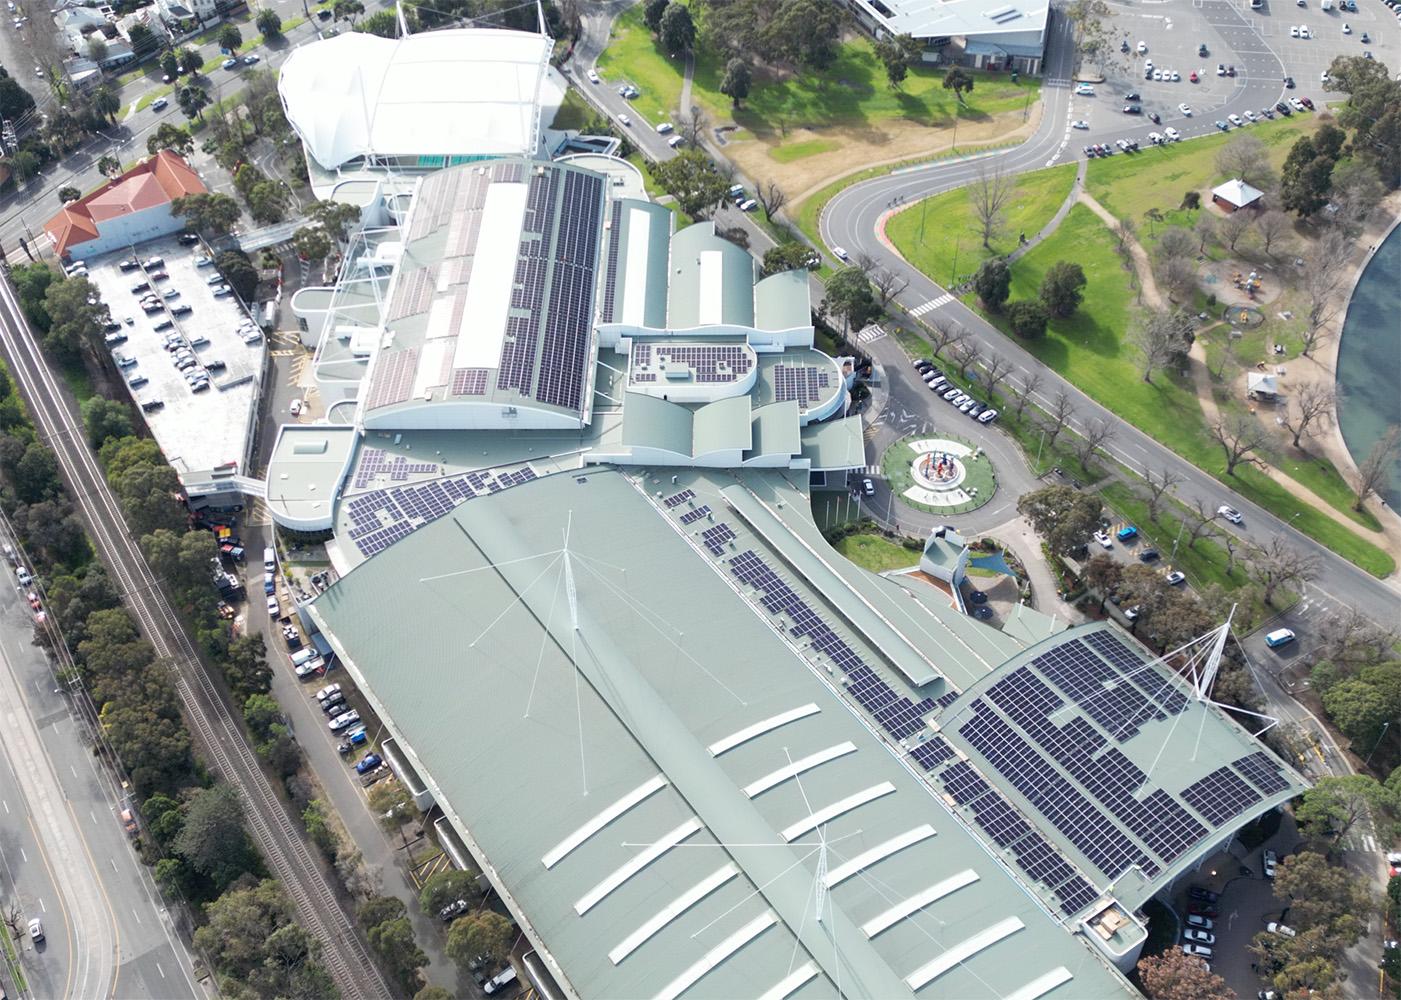
A 1.3 MW rooftop solar system installed at the Melbourne Sports and Aquatic Centre demonstrates that curved, shaded and structurally constrained commercial roofs can be harnessed for solar generation. Advanced module technology and site-specific engineering allowed the array to be 53% larger than the initial tender and 60% larger than a conventional design that would have avoided shading. The article notes that Australia has installed 22 GW of rooftop solar on homes but only 5.6 GW on commercial and industrial buildings, despite businesses using more electricity and more of it during daylight hours. Industry estimates suggest 40 GW of technical rooftop potential exists across C&I buildings, yet forecasts point to only 17, 31 GW by 2050. Many commercial roofs remain undersized because they are curved, shaded or structurally limited, and standard industry practice is to design around those constraints rather than engineer through them.
Where this fits
This story bears on cost and materials dependency. Capturing the full rooftop potential requires more advanced panels and engineering per megawatt installed. Those modules and the inverters to manage their performance are sourced largely from China. A larger rooftop solar fleet means proportionally larger embedded demand for Chinese-manufactured silicon, cell-processing capacity, and inverter supply, adding to grid-level material exposure and supply-chain risk with no improvement to firm capacity.
What it means
Expanding solar into difficult roofs is technically feasible and may reduce grid-demand peaks during daylight. But it does not address the core problem: weather-dependent generation still requires gas or storage for evening and cloudy-day firming, and those costs scale with total solar deployment. The harder Australia pushes rooftop solar to its limits, the more it entrenches reliance on China's renewable supply chain and on gas backup. A firm, dispatchable generation source, nuclear is the lowest-emission alternative, remains unavailable by law.
By the numbers
at ~A$1100–1600/kW installed. Source: CSIRO GenCost 2024-25. Indicative.
at a ~24% capacity factor, and only when the sun shines, so it still needs firming.
~80% of modules are China-made. Source: IEA solar supply-chain data.
enough for 1–2 TWh a year of firm, always-on power, generating for ~60 years. Source: CSIRO GenCost 2024-25 (A$8.5–13.2bn/GW), IAEA capacity factor.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
at ~A$1100–1600/kW installed. Source: CSIRO GenCost 2024-25. Indicative.
at a ~24% capacity factor, and only when the sun shines, so it still needs firming.
~80% of modules are China-made. Source: IEA solar supply-chain data.
enough for 14–33 TWh a year of firm, always-on power, generating for ~60 years. Source: CSIRO GenCost 2024-25 (A$8.5–13.2bn/GW), IAEA capacity factor.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
Go deeper on the numbers
The bigger picture
Energy security is national security. This connects to the wider case at Unprepared: Australia's dependence on a strategic rival, and how ready it is for the world that is coming.
Reported by PV Magazine Australia. Read the original report ↗
Related coverage
Snowy 2.0: A monument to this nation’s energy policy hubris - The Australian
Gas reserve ‘could blow away $330bn’ - The Australian
It might not feel like it, but our power is among the world’s cheapest - AFR
First new steel mill in Australia in 35 years to be the first to be powered by 100 per cent renewables - Renew Economy
The numbers, as they move
A short, sourced brief when the figures shift: a transmission blow-out, a supply-chain move, a milestone.