Atmos adds BayWa r.e. projects to expanding renewables portfolio
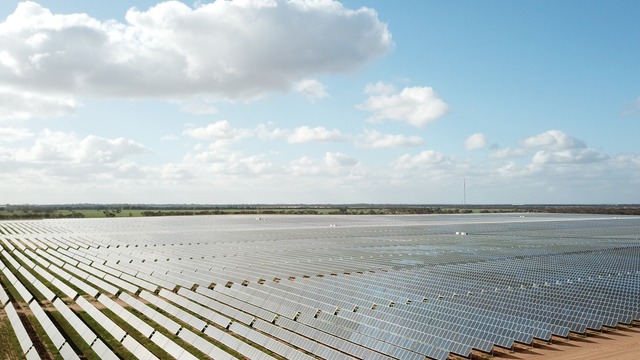
Atmos Renewables, the investment arm of Igneo Infrastructure Partners, has acquired a portfolio of operating solar and wind assets and early-stage projects from German developer BayWa r.e., including the 106 MW Yatpool Solar Farm in Victoria, the 20 MW Hughenden Solar Farm in Queensland, and the advanced Bullawah Wind Farm project in NSW with access rights for 262 MW. The deal lifts Atmos' operational and in-construction capacity beyond 2 GW across 19 assets. BayWa r.e. is withdrawing from Australia to focus on European operations.
Where this fits
This transaction illustrates the consolidation of Australia's renewables base into a narrower investor class and a dependency on international capital and developer appetite. It also underscores the ongoing build-out of weather-dependent generation, which requires matching investment in gas-fired firming and transmission infrastructure not captured in the headline. The Bullawah project, despite its scale, remains limited to 262 MW of wind access by grid constraints, a sign of the transmission bottlenecks that pile whole-system costs onto a renewables-heavy grid.
What it means
Australia's energy transition continues to rely on foreign investors and European developers deciding when and where to operate in the country. Renewables scaling does not solve the firming problem: each megawatt of wind and solar built adds latent demand for gas peaking capacity or battery storage, multiplying the materials chain through China and extending the build-out timeline. A firm, domestically controllable alternative, nuclear, remains off the table by law, leaving Australia locked into the cost and security profile of a weather-dependent grid.
By the numbers
at ~A$1100–1600/kW installed. Source: CSIRO GenCost 2024-25. Indicative.
at a ~24% capacity factor, and only when the sun shines, so it still needs firming.
~80% of modules are China-made. Source: IEA solar supply-chain data.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
at ~A$600–1000/kWh installed. Source: BNEF, CSIRO GenCost 2024-25. Indicative.
of average national (NEM) demand if fully dischargeable, then it needs recharging. Storage shifts power, it does not generate it.
lithium, graphite, nickel, copper and cobalt (~72 t lithium content). Replaced roughly every 12 years. Source: IEA, Argonne GREET. Indicative.
~75% of cells are China-made. Source: IEA cell-manufacturing share.
enough for 0–1 TWh a year of firm, always-on power, generating for ~60 years. Source: CSIRO GenCost 2024-25 (A$8.5–13.2bn/GW), IAEA capacity factor.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
Go deeper on the numbers
The bigger picture
Energy security is national security. This connects to the wider case at Unprepared: Australia's dependence on a strategic rival, and how ready it is for the world that is coming.
Reported by PV Magazine Australia. Read the original report ↗
Related coverage
Snowy 2.0: A monument to this nation’s energy policy hubris - The Australian
Gas reserve ‘could blow away $330bn’ - The Australian
It might not feel like it, but our power is among the world’s cheapest - AFR
First new steel mill in Australia in 35 years to be the first to be powered by 100 per cent renewables - Renew Economy
The numbers, as they move
A short, sourced brief when the figures shift: a transmission blow-out, a supply-chain move, a milestone.