Atmos reaches financial close on 870 MW of renewables projects
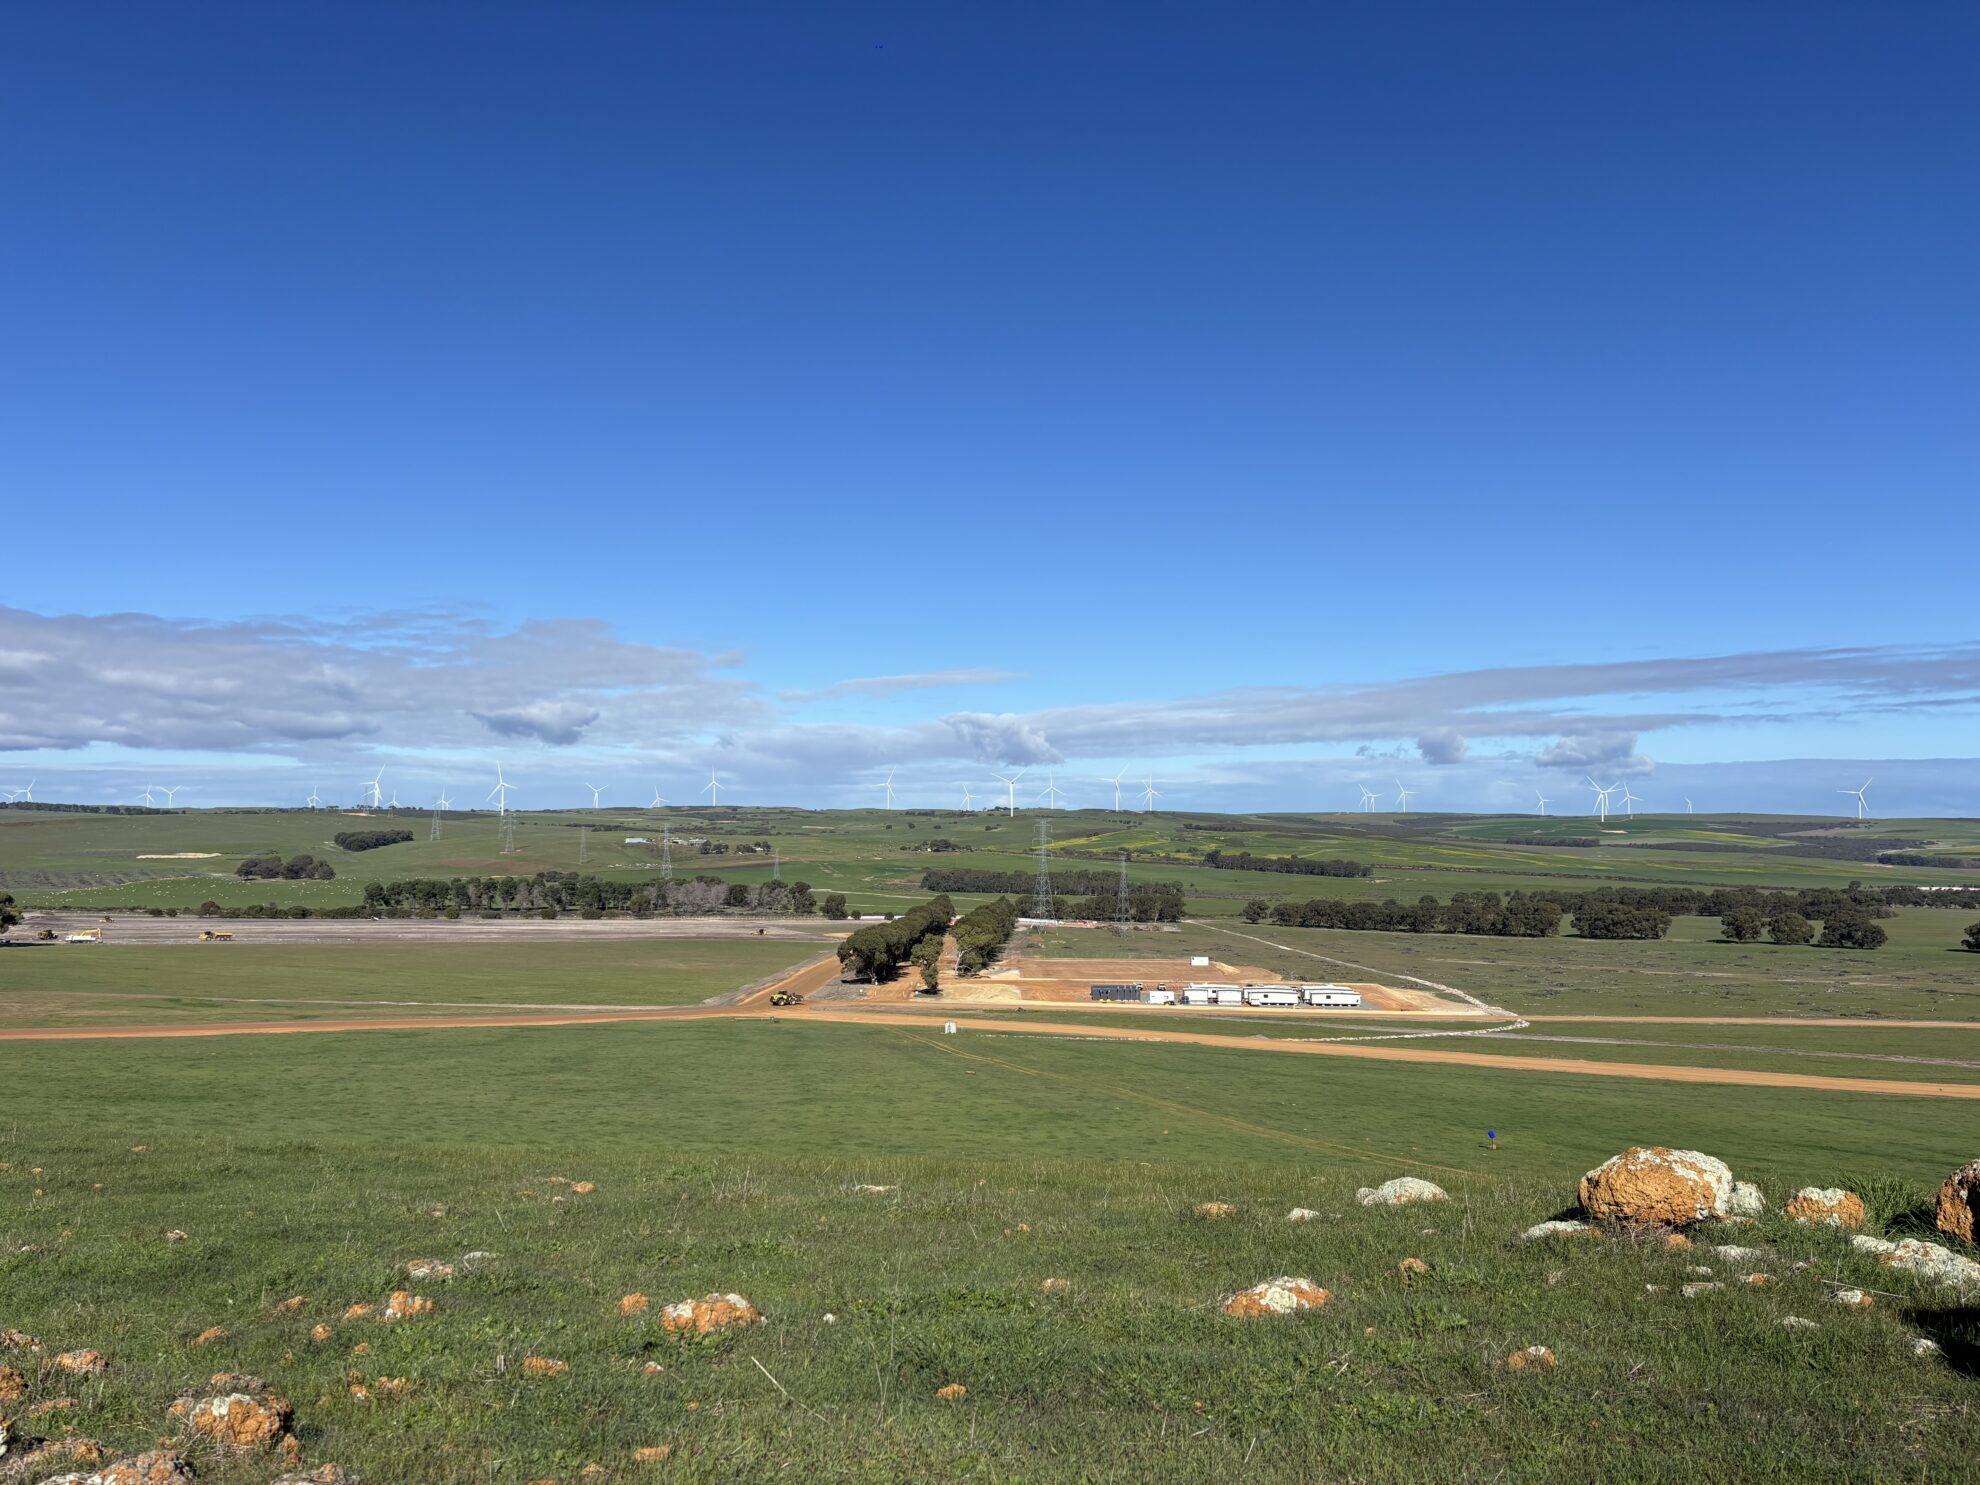
Atmos Renewables has reached financial close on 870 MW of new renewable capacity: a 400 MW battery energy storage system (BESS) on Queensland's Fraser Coast, and a 470 MW wind farm in Western Australia's Wheatbelt. Combined cost is $2.9 billion. Both projects are supported by the Australian government's Capacity Investment Scheme. The battery is expected to start operations in 2028. The wind farm has a long-term power purchase agreement with Western Australian state utility Synergy. Construction of both is expected to commence soon.
Where this fits
This is a data point on the firming cost. The Teebar BESS alone costs $2.9 billion for 400 MW and four hours of storage. That is the infrastructure needed to prop up wind output when weather fails. It is not additional generation; it is the system cost of relying on weather-dependent supply. The battery will help "meet market needs for the firming capacity required in Australia" as the headline notes. That firming capacity, and its capital cost, is invisible in the headline "870 MW of renewables" but it is the real constraint on a grid built from wind and solar alone.
What it means
Australia is now building dual grids: one for generation when conditions permit, one (batteries, gas, transmission overbuild) to firm that generation when they do not. Each dollar spent on Teebar is a dollar not spent on firm, dispatchable capacity that requires no weather window and no battery. Nuclear would deliver both roles, generation and firm support, in a single plant, with lower lifecycle emissions, no Chinese supply-chain dependence, and a 60-year asset life versus a battery's 10-15 years. Instead, firming batteries are being financed as a separate, repeating cost centre.
By the numbers
at ~A$600–1000/kWh installed. Source: BNEF, CSIRO GenCost 2024-25. Indicative.
of average national (NEM) demand if fully dischargeable, then it needs recharging. Storage shifts power, it does not generate it.
lithium, graphite, nickel, copper and cobalt (~160 t lithium content). Replaced roughly every 12 years. Source: IEA, Argonne GREET. Indicative.
~75% of cells are China-made. Source: IEA cell-manufacturing share.
enough for 1–1 TWh a year of firm, always-on power, generating for ~60 years. Source: CSIRO GenCost 2024-25 (A$8.5–13.2bn/GW), IAEA capacity factor.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
at ~A$2000–3200/kW installed. Source: CSIRO GenCost 2024-25. Indicative.
at a ~38% capacity factor, and only when the wind blows, so it still needs firming.
enough for 1–1 TWh a year of firm, always-on power, generating for ~60 years. Source: CSIRO GenCost 2024-25 (A$8.5–13.2bn/GW), IAEA capacity factor.
Figures are indicative conversions from the article's stated quantity using published cost, material and capacity factors (CSIRO GenCost, BNEF, IEA, IAEA). Ranges, not precise forecasts.
Go deeper on the numbers
The bigger picture
Energy security is national security. This connects to the wider case at Unprepared: Australia's dependence on a strategic rival, and how ready it is for the world that is coming.
Reported by PV Magazine Australia. Read the original report ↗
Related coverage
More batteries, both big and small, mean solar farms don’t have to shut down so often - Renew Economy
Concrete foundations completed for all 18 turbines at first and smallest wind farm to begin construction this year
Australia’s gas generation falls to lowest level since 2000 — OilPrice - UA.NEWS
Renewables Boom Pushes Australia's Gas Power to Quarter-Century Low - Crude Oil Prices Today | OilPrice.com
The numbers, as they move
A short, sourced brief when the figures shift: a transmission blow-out, a supply-chain move, a milestone.